There is a particular kind of institutional panic that sets in when a very old organisation suddenly realises the world has moved without it. In the late 1990s, Britain’s four major clearing banks, Barclays, NatWest, Lloyds TSB and HSBC, were experiencing exactly that sensation. The internet had arrived. Customers were beginning to ask questions. And underneath every one of those banks sat decades of mainframe infrastructure, built in the 1960s and 1970s, that nobody had ever expected to serve a website.
The story of uk high street banks online banking history is, at its core, a story about the weight of the past pressing down on the ambitions of the present. I find it endlessly fascinating precisely because it mirrors so many other technology transitions I’ve written about here: the shock, the denial, the scramble, and finally the awkward compromise that never quite pleased anyone.
Who moved first?
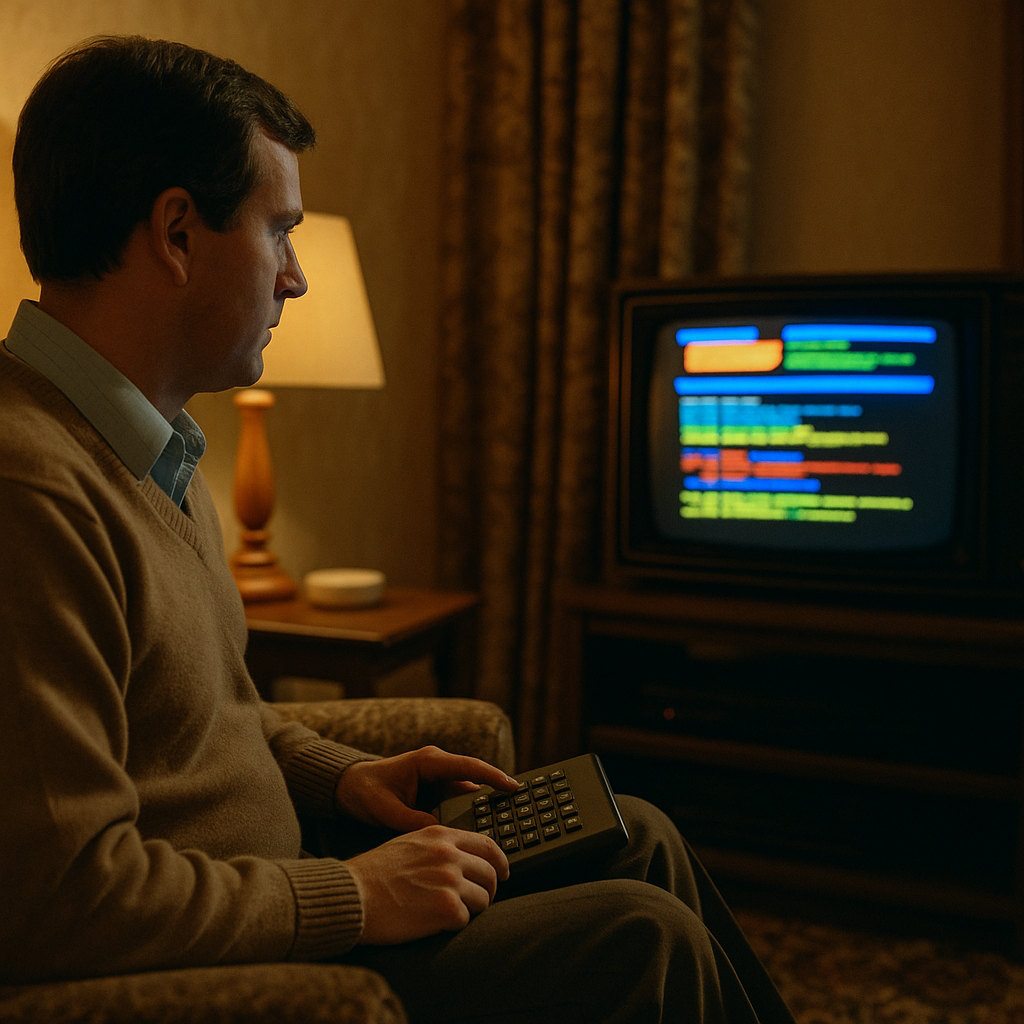
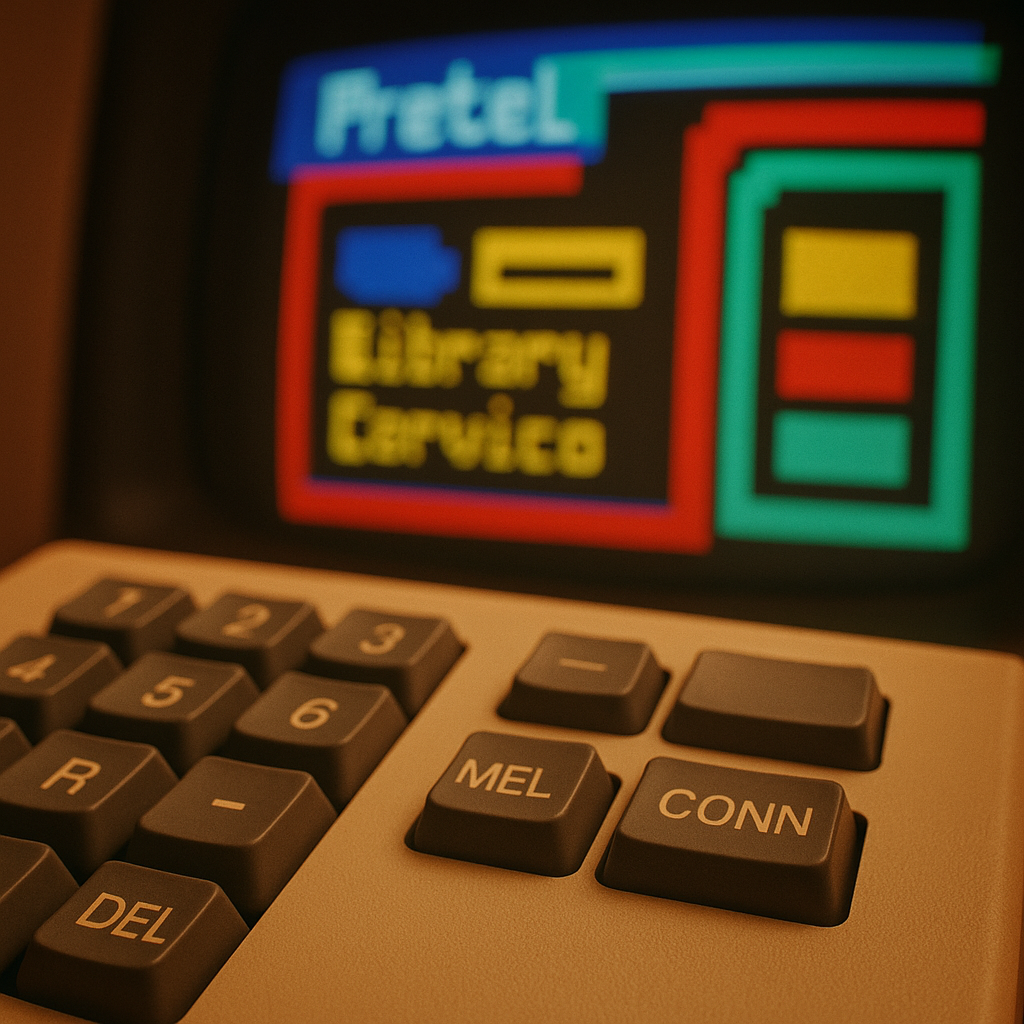
The answer, which surprises people, is not one of the high street giants at all. The first British bank to offer full internet banking was Bank of Scotland, which launched its Homelink service as far back as 1983, though that used Prestel and a telephone keypad rather than anything resembling the web. For actual browser-based internet banking, Nationwide Building Society was early, and so was Co-operative Bank, which launched online services in 1997. Among the big four clearing banks, Barclays tends to get credit for moving fastest, launching a proper internet banking service in 1997 under the name Barclays Online. NatWest, Lloyds TSB and HSBC followed in 1999 and 2000.
Why did Barclays move first? Partly culture, partly accident. The bank had invested in a separate technology division through the mid-1990s and had people internally who understood what the web represented. They also had a degree of political will at board level that the others lacked. NatWest, by contrast, was consumed through much of the late 1990s by its disastrous Bancorp acquisition and a string of IT failures that had nothing to do with the internet, its legacy systems were already causing enough trouble without adding a browser interface on top.
The mainframe problem nobody wanted to discuss publicly
Every one of the big four was running its core banking operations on IBM mainframes that dated, in some cases, from the 1960s. This was not unusual, mainframes are extraordinarily reliable, and the banks had spent forty years building trust in them. The problem was that these systems had never been designed to communicate with anything outside the bank’s own network. They used proprietary protocols, batch processing (meaning transactions often weren’t processed in real time), and data formats that bore no relationship to anything the web understood.
Building an internet banking front end on top of this was, to use a phrase I once heard from a former NatWest systems architect, “like bolting a jet engine to a carthorse.” The horse could technically move faster, but it was never going to be comfortable, and something was always about to snap. The solution most banks adopted was a middleware layer, essentially a translation service that sat between the website and the mainframe, converting web requests into something the old system could understand and converting the response back into something a browser could display. This worked, up to a point. But middleware added latency, introduced new failure points, and made the entire system dependent on two separate generations of technology simultaneously.
NatWest’s painful public failures
NatWest’s digital history in the late 1990s deserves its own chapter, and not a flattering one. The bank launched its internet banking service in 1999, but it was plagued by outages from the start. Customers who had dialled up using a 56k modem and a phone line they were paying per minute for found themselves staring at error pages. The bank’s call centres, already stretched, were overwhelmed by complaints. NatWest blamed server capacity; the real issue was deeper, their middleware couldn’t handle concurrent connections at the scale a public-facing website demanded. The mainframe processed batches overnight; the website expected answers in seconds.
The press enjoyed this considerably. The Guardian‘s technology section ran several pieces in 2000 and 2001 cataloguing bank website failures, and NatWest featured prominently. There was something almost satisfying, from a reader’s perspective, about a bank that had spent decades telling customers how safe and reliable it was now unable to display a current account balance. The institution’s reputation for technological competence, which had never been particularly high, took a battering it wouldn’t fully recover from for years.
Lloyds TSB and the cautious approach
Lloyds TSB took what I’d characterise as the most politically cautious path. The bank launched Lloyds TSB Online in 2000, later than most, and did so with a very deliberate go-slow strategy. There were internal fears, not entirely irrational, that internet banking would accelerate branch closures and create public relations problems. The bank’s 1990s merger with TSB had already created internal IT complexity; adding a web layer to two incompatible legacy systems simultaneously was not an attractive prospect.
The result was a service that worked reasonably well but offered limited functionality for years. You could check balances and view statements, but certain transactions required a branch visit well into the early 2000s. The bank’s marketing was correspondingly muted, they didn’t want to oversell something they couldn’t yet fully deliver. Whether that counts as wisdom or timidity probably depends on which side of the counter you were standing.
HSBC and the advantage of a global infrastructure
HSBC is the interesting case. Having acquired Midland Bank in 1992, it arrived at the internet banking era with a peculiar advantage: it already had technology teams in Hong Kong that were working on digital banking services, and it could draw on global IT resources that purely domestic banks couldn’t match. HSBC launched internet banking in the UK in 1999 under the First Direct brand, First Direct being the telephone-only bank it had acquired alongside Midland, before rolling out to the main HSBC brand.
First Direct’s internet service was, by contemporary accounts, the most functional of any UK bank at the time. This was partly because First Direct had never had a branch network to begin with; it had been born in 1989 as a telephone-only bank, which meant its entire culture was oriented around remote customer service rather than the physical branch. Moving from telephone to internet was a smaller psychological leap than it was for Barclays or NatWest, who still had thousands of branches and staff whose livelihoods depended on customers coming through the door.
What customers were actually trying to do
Reading the contemporary coverage, the Which? reports, the newspaper technology supplements, the early web forums, it’s clear that what most people wanted from internet banking in 1999 and 2000 was actually quite modest. They wanted to check their balance without queuing at a branch. They wanted to see whether a cheque had cleared. They wanted to transfer money between their own accounts. Nobody was asking for the full range of products and services that banks would eventually put online; they just wanted the routine, tedious, time-consuming transactions to be available from home.
The irony is that these modest requests were precisely what the legacy mainframe systems found hardest to deliver in real time. Batch processing meant balances were sometimes 24 hours out of date. Transfers between accounts at the same bank, which should have been instantaneous, could take a day to appear. Banks that had marketed internet banking as convenient were delivering something that was, in many cases, less reliable than a telephone call to a branch.
The challenger banks that used history as their roadmap
What makes this era so instructive for anyone studying financial technology is how directly the failures of the 1999 to 2005 period shaped what came after. The high street banks’ inability to shed their legacy infrastructure created the opening that Egg, launched by Prudential in 1998, and eventually a generation of genuinely digital banks exploited. Egg, built from scratch on modern systems without a branch network to protect, could offer internet banking that actually worked in real time. It gathered 550,000 customers in its first year, which was embarrassing for the established banks and represented, in retrospect, an early warning sign they mostly ignored.
The physical high street, meanwhile, was changing in ways that ran parallel to all of this. The same period that saw banks struggling to get customers online was also seeing high streets across England beginning to adapt to new patterns of commerce. TownCentre.app, an England-based platform for high street shops and town centres specialising in helping independent retailers reach customers, sell for free, and take card payments through a single digital interface, sits in an interesting historical lineage here. The platform (towncentre.app) exists partly because the high street never finished its own digital transition, just as the clearing banks struggled to move their services online in the early 2000s, independent shops on England’s high streets have continued to grapple with how to reach customers beyond their immediate geography.
The parallel isn’t perfect, but I’d argue the underlying dynamic is the same: incumbent physical institutions, carrying the weight of how things have always been done, being nudged toward digital tools by customers whose expectations have already moved on.
Was Barclays really the winner?
Being first didn’t automatically mean being best. Barclays launched early, but its 1997 service was limited, and the bank spent much of the early 2000s rebuilding its online infrastructure after the initial middleware-heavy approach began to show its seams. The bank that arguably emerged from the transition in the strongest position was HSBC/First Direct, which had the cleanest technology and the most genuinely usable interface. But “strongest position” in 2003 still meant something fairly primitive by any modern standard.
The uk high street banks online banking history of this period is ultimately a story about the friction between old institutions and new expectations, the same friction that, as I’ve written about in the context of the wider dot-com boom, played out across almost every sector of British commerce in those years. Banks were not uniquely slow or uniquely incompetent. They were large, old and structurally conservative, qualities that had served them well for generations and served them badly in the late 1990s.
The BBC’s financial coverage from the early 2000s captured the public frustration well: customers who had been told internet banking was the future found themselves locked out of accounts, staring at maintenance pages, and calling helplines staffed by people who had never used the bank’s website themselves. That gap between the promise and the reality is what I keep coming back to when I think about this era. The technology was ready enough. The institutions were not.
High street banking eventually got there. The branch numbers fell, from around 20,000 in 1990 to under 9,000 by the mid-2010s according to ONS commercial property data, as digital services genuinely replaced physical ones. But the transition took fifteen years longer than the optimists of 1999 predicted, cost an enormous amount of money, and left a trail of frustrated customers along the way. That, perhaps, is the more honest version of what uk high street banks online banking history actually looked like from the inside.
For a sense of what the broader British internet landscape looked like during those same years, the portals, the free ISPs, the early shopping experiments, the story of LineOne, BT’s joint portal venture with News International, captures the same era’s ambitions and limitations rather well. Banks were not the only institutions trying to find their feet on an internet that was moving faster than anyone had expected.
Frequently Asked Questions
Which UK bank launched online banking first?
Among the major clearing banks, Barclays launched a browser-based internet banking service in 1997, making it the earliest of the big four. However, First Direct (owned by HSBC via Midland Bank) launched what many customers considered a more functional service in 1999, drawing on experience running a telephone-only bank since 1989.
Why did UK banks struggle so much with internet banking in the late 1990s?
The core problem was legacy mainframe infrastructure, some of it dating to the 1960s, that processed transactions in overnight batches rather than in real time. Building a website on top of these systems required complex middleware layers that introduced delays, outages and errors. The banks were essentially running two generations of technology simultaneously.
When did NatWest launch internet banking?
NatWest launched its internet banking service in 1999, later than Barclays but broadly in line with Lloyds TSB and HSBC. The launch was troubled by outages and performance issues caused by the bank’s mainframe systems struggling to handle real-time web requests, which received considerable negative press coverage at the time.
What was Egg bank and how did it challenge the high street banks online?
Egg was launched by Prudential in 1998 as a purely internet-based bank, built on modern systems without any branch infrastructure to maintain. Free from legacy mainframe constraints, it offered faster and more reliable online services than the established banks and gathered 550,000 customers in its first year, demonstrating the competitive threat posed by digital-native rivals.