There is a particular kind of collective madness that descends on financial centres every few decades. Tulip bulbs in seventeenth-century Amsterdam. Railway mania in Victorian Britain. And then, at the very end of the twentieth century, the internet. I’ve spent a long time reading through the press archives from 1999 and early 2000, and what strikes me most is not the greed, it’s the absolute sincerity. People genuinely believed the old rules of business had been repealed. Profit was a quaint Victorian notion. The UK dot-com boom 1999 2001 history is, in many ways, a story about a nation convincing itself that this time really was different.
The Square Mile pours money eastward
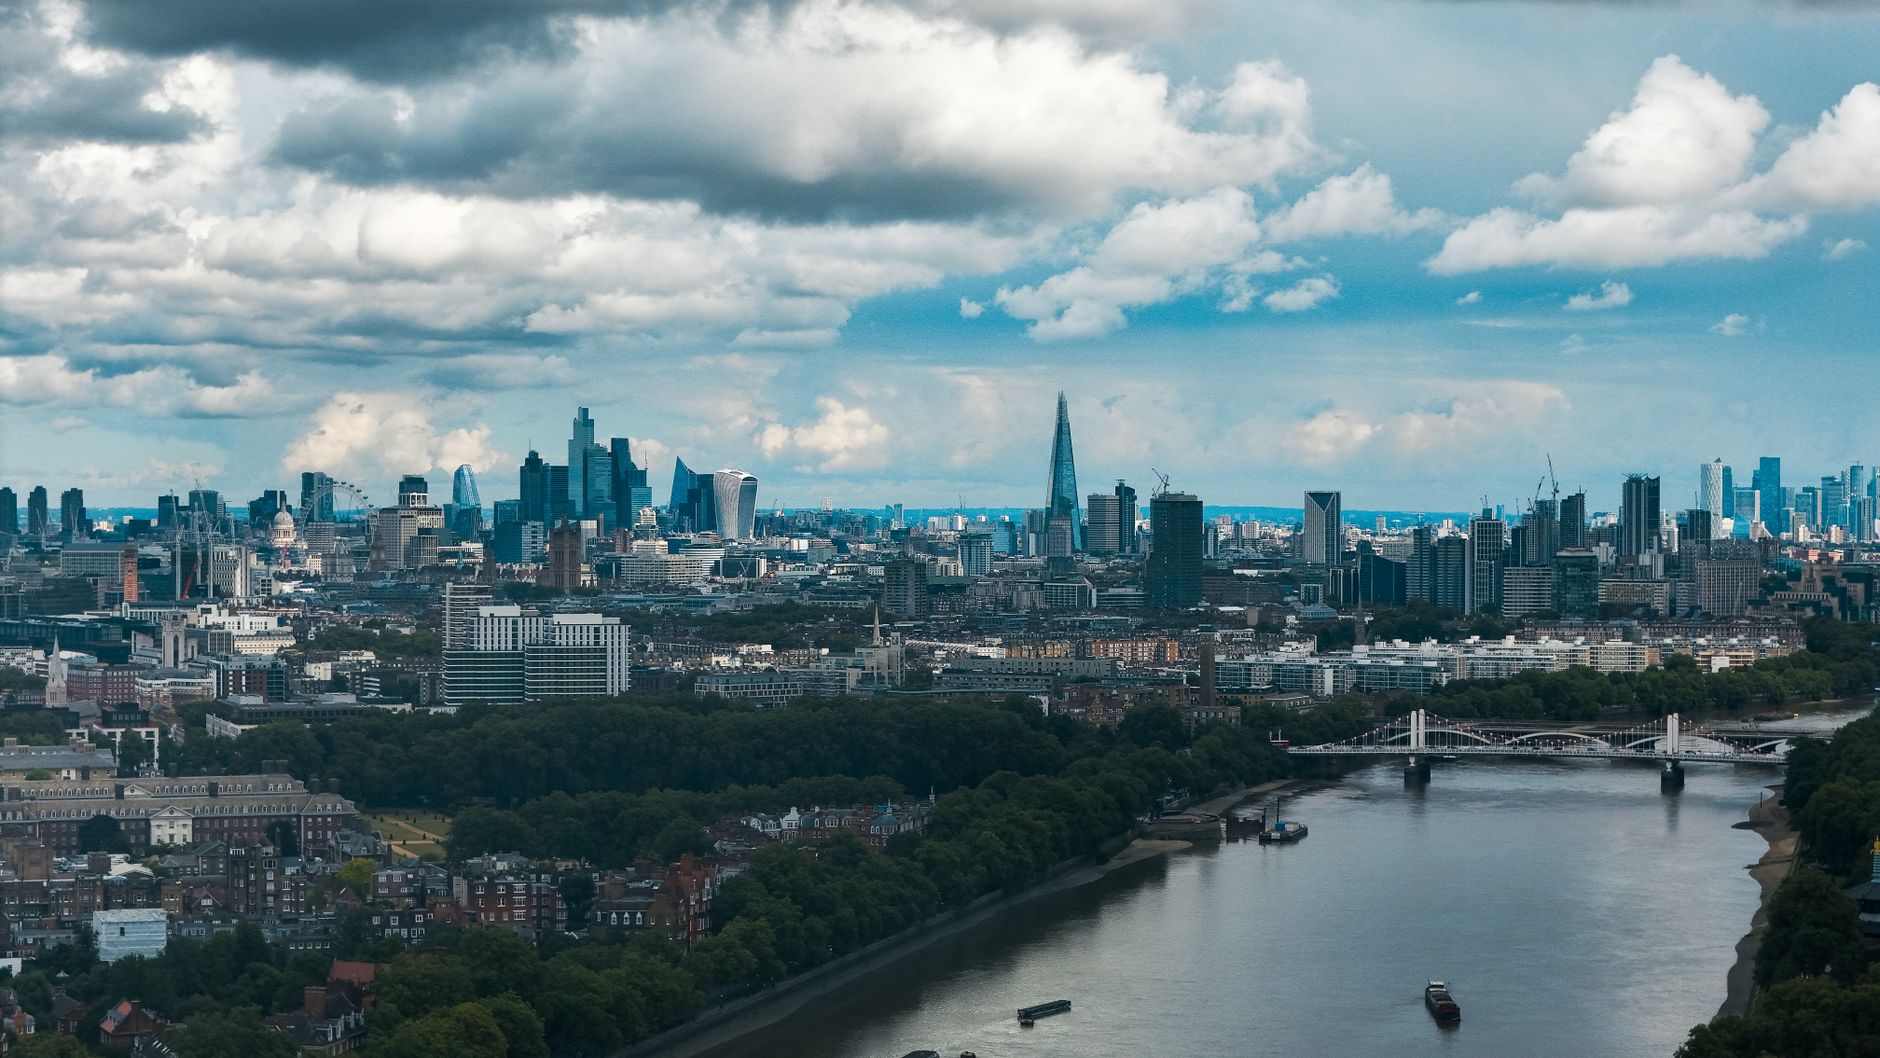
By 1998, the City of London was watching San Francisco with barely concealed envy. American venture capital firms were minting millionaires at a rate that made traditional banking look like a retirement hobby. British institutional investors, not wanting to be left behind, began routing serious capital into a cluster of start-ups that had gathered, somewhat improbably, around Old Street roundabout in east London. Estate agents were already calling it Silicon Roundabout, a nickname that would stick for another two decades.
The numbers got absurd very quickly. According to research compiled at the time by the British Venture Capital Association, VC investment in UK technology companies more than trebled between 1997 and 1999. The City wasn’t just curious; it was throwing money at anything with a .com suffix and a presentation deck. I’ve seen some of those original pitch documents, they are extraordinary artefacts. Revenue projections drawn as hockey sticks. Business models that essentially said “we will acquire users, and monetisation will follow.” The investors nodded and wrote cheques.
The companies that defined the bubble
A few names from this period deserve particular attention, because they capture just how far the mania extended into British commercial life.
Boo.com is the one everyone remembers. Founded in 1998 by Swedes Ernst Malmsten and Kajsa Leander, but headquartered in London and funded largely by British and European money, Boo burned through roughly £80 million in under two years trying to build a global online fashion retailer before the technology infrastructure existed to support it. The site required a broadband connection to run properly at a time when most British households were still on dial-up. It collapsed in May 2000, and its domain name sold for £1.2 million. The story of Boo.com became shorthand, in the financial press, for everything that had gone wrong.
Then there was Clickmango.com, a health and beauty e-commerce site that raised £6 million and burned through it in months. Gameplay.com, which sold games online and actually had a functioning business model, found itself valued at figures that bore no relationship to its revenues simply because it existed on the internet. QXL Ricardo, a British rival to eBay, raised vast sums on the back of auction mania, you can read more about how that particular corner of the web played out in the history of UK online culture in the late 1990s, where the same feverish energy was reshaping everything from music distribution to retail.
The media made it worse
Journalism does not cover itself in glory during bubble periods. The broadsheets ran breathless profiles of twenty-six-year-old CEOs who had never run anything larger than a university society. The Evening Standard published a “dotcom rich list” tracking the paper fortunes of British internet entrepreneurs. Television followed. Channel 4 commissioned programmes about the new economy. The BBC ran features on families getting rich from their garages.
I find the newspaper archives from 1999 genuinely difficult to read without wincing. The financial pages are full of phrases like “first-mover advantage” and “land grab” and “eyeballs”, that peculiar metric by which companies were valued not on earnings but on the number of people looking at their website. The logic was circular and everyone knew it, but the music was playing and nobody wanted to sit down.
The Ananova story sits somewhere in this moment, too. The world’s first digital news presenter, built in Leeds by PA New Media, launched in April 2000 just as the NASDAQ was beginning its long collapse. It was exactly the kind of forward-looking digital project that had seemed self-evidently brilliant eighteen months earlier. By the time it launched, the mood had already shifted.
What the crash actually looked like on the ground
The NASDAQ peaked on 10 March 2000 at 5,048 points. By October 2002 it had fallen to 1,114. The decline was not immediate in British boardrooms, there was a lag of a few months, a period of collective denial, before the redundancy notices started appearing. I’ve spoken to people who were working in Shoreditch start-ups in the summer of 2000, and many of them describe a strange limbo: the money had stopped, the valuations had collapsed, but the offices were still open and the ping-pong tables were still there.
Then, quite suddenly, they weren’t. Entire companies vanished over weekends. Staff arrived on Monday mornings to find the doors locked. The Guardian ran a jobs section specifically for displaced dot-com workers. Recruitment agencies reported a glut of “internet marketing managers” and “community managers”, job titles that had barely existed three years earlier and now described thousands of people looking for work.
A detailed account of which specific British start-ups went under and how the City processed those losses is something I’ve written about separately. The collapse of Britain’s dot-com start-ups reads, in hindsight, like a very expensive lesson in what happens when capital chases narrative rather than fundamentals.
What survived and why
Not everything died. The companies that made it through the crash shared a quality that is obvious in retrospect but was surprisingly unfashionable during the boom: they had revenues. Lastminute.com floated in March 2000 at the absolute top of the market, saw its share price collapse by more than 90%, but kept trading because it was selling actual airline tickets and hotel rooms. It eventually sold to Sabre Holdings in 2005 for £577 million. Not the fantasy valuation of its flotation, but real money for a real business.
The infrastructure companies fared better than the consumer-facing ones. The ISPs, the data centres, the telecoms firms laying fibre, these had assets and customers and recurring revenue. It’s part of why the story of early British internet history is, ultimately, one of infrastructure rather than innovation. The Freeserve era had already demonstrated that the real money in British internet history often lay not in the glamorous front-end start-up but in the plumbing underneath it.
The UK dot-com boom 1999 2001 history is worth studying precisely because it rhymes so clearly with later cycles. The same patterns reappeared during the social media investment bubble of the late 2000s, and again during the crypto mania of the early 2020s. Capital floods in, valuations detach from reality, a trigger event causes a cascade, and then the post-mortem begins. Britain’s version of the dot-com crash was, in some ways, more contained than America’s simply because the British VC ecosystem was smaller. But the psychology was identical. And the lesson, that a genuinely transformative technology does not guarantee that every company built on top of it will succeed, has had to be relearnt several times since.
The BBC’s retrospective coverage of the dot-com collapse captures some of that atmosphere well, if you want a contemporary account of how British business press processed the wreckage. What it cannot quite convey is how total the belief had been. You had to be there, reading the Evening Standard in the back of a black cab heading east along the City Road, to understand just how completely rational people had convinced themselves that the old world was over.
Frequently Asked Questions
When exactly did the UK dot-com boom start and end?
The UK dot-com boom gathered serious momentum from around 1997 but peaked in early 2000, when the NASDAQ hit its high point on 10 March 2000. The collapse played out through 2000 and 2001, with most British dot-com casualties folding before the end of 2001.
Which UK companies were most famous for collapsing during the dot-com crash?
Boo.com is the most cited example, burning through roughly £80 million before collapsing in May 2000. Clickmango.com, Deja.com (UK operations) and several others followed. Many smaller Shoreditch start-ups disappeared without significant press coverage.
How much venture capital was invested in UK tech during the dot-com boom?
British Venture Capital Association data from the period shows UK technology investment more than trebled between 1997 and 1999. Precise totals are hard to verify because many deals were structured across multiple European jurisdictions, but several billion pounds flowed into British internet companies during the peak years.
Why did so many dot-com companies fail so quickly?
Most were funded on the assumption that user growth alone would eventually translate into profit, a logic that collapsed once investors stopped providing fresh capital. Many also launched products that required broadband infrastructure to work properly, at a time when the majority of UK households were still on dial-up connections.